When prices rise, cash loses purchasing power. The grocery bill climbs, rent goes up, and money sitting in a savings account buys a little less every year. That’s why so many people search for a reliable real estate inflation hedge, a way to own something whose income and value can keep pace with rising prices.
Real estate has a long track record in this role. Property values and rents tend to rise with the broader cost of living over time, and some property types can adjust their income faster than others. But not every property protects against inflation in the same way, and owning real estate directly comes with its own costs and responsibilities.
This guide explains why real estate is often considered a strong inflation hedge, which property types adjust fastest, what to review before choosing a property, and how professionally managed fractional ownership through Vairt lets you own inflation-responsive properties like hotels without managing them yourself.
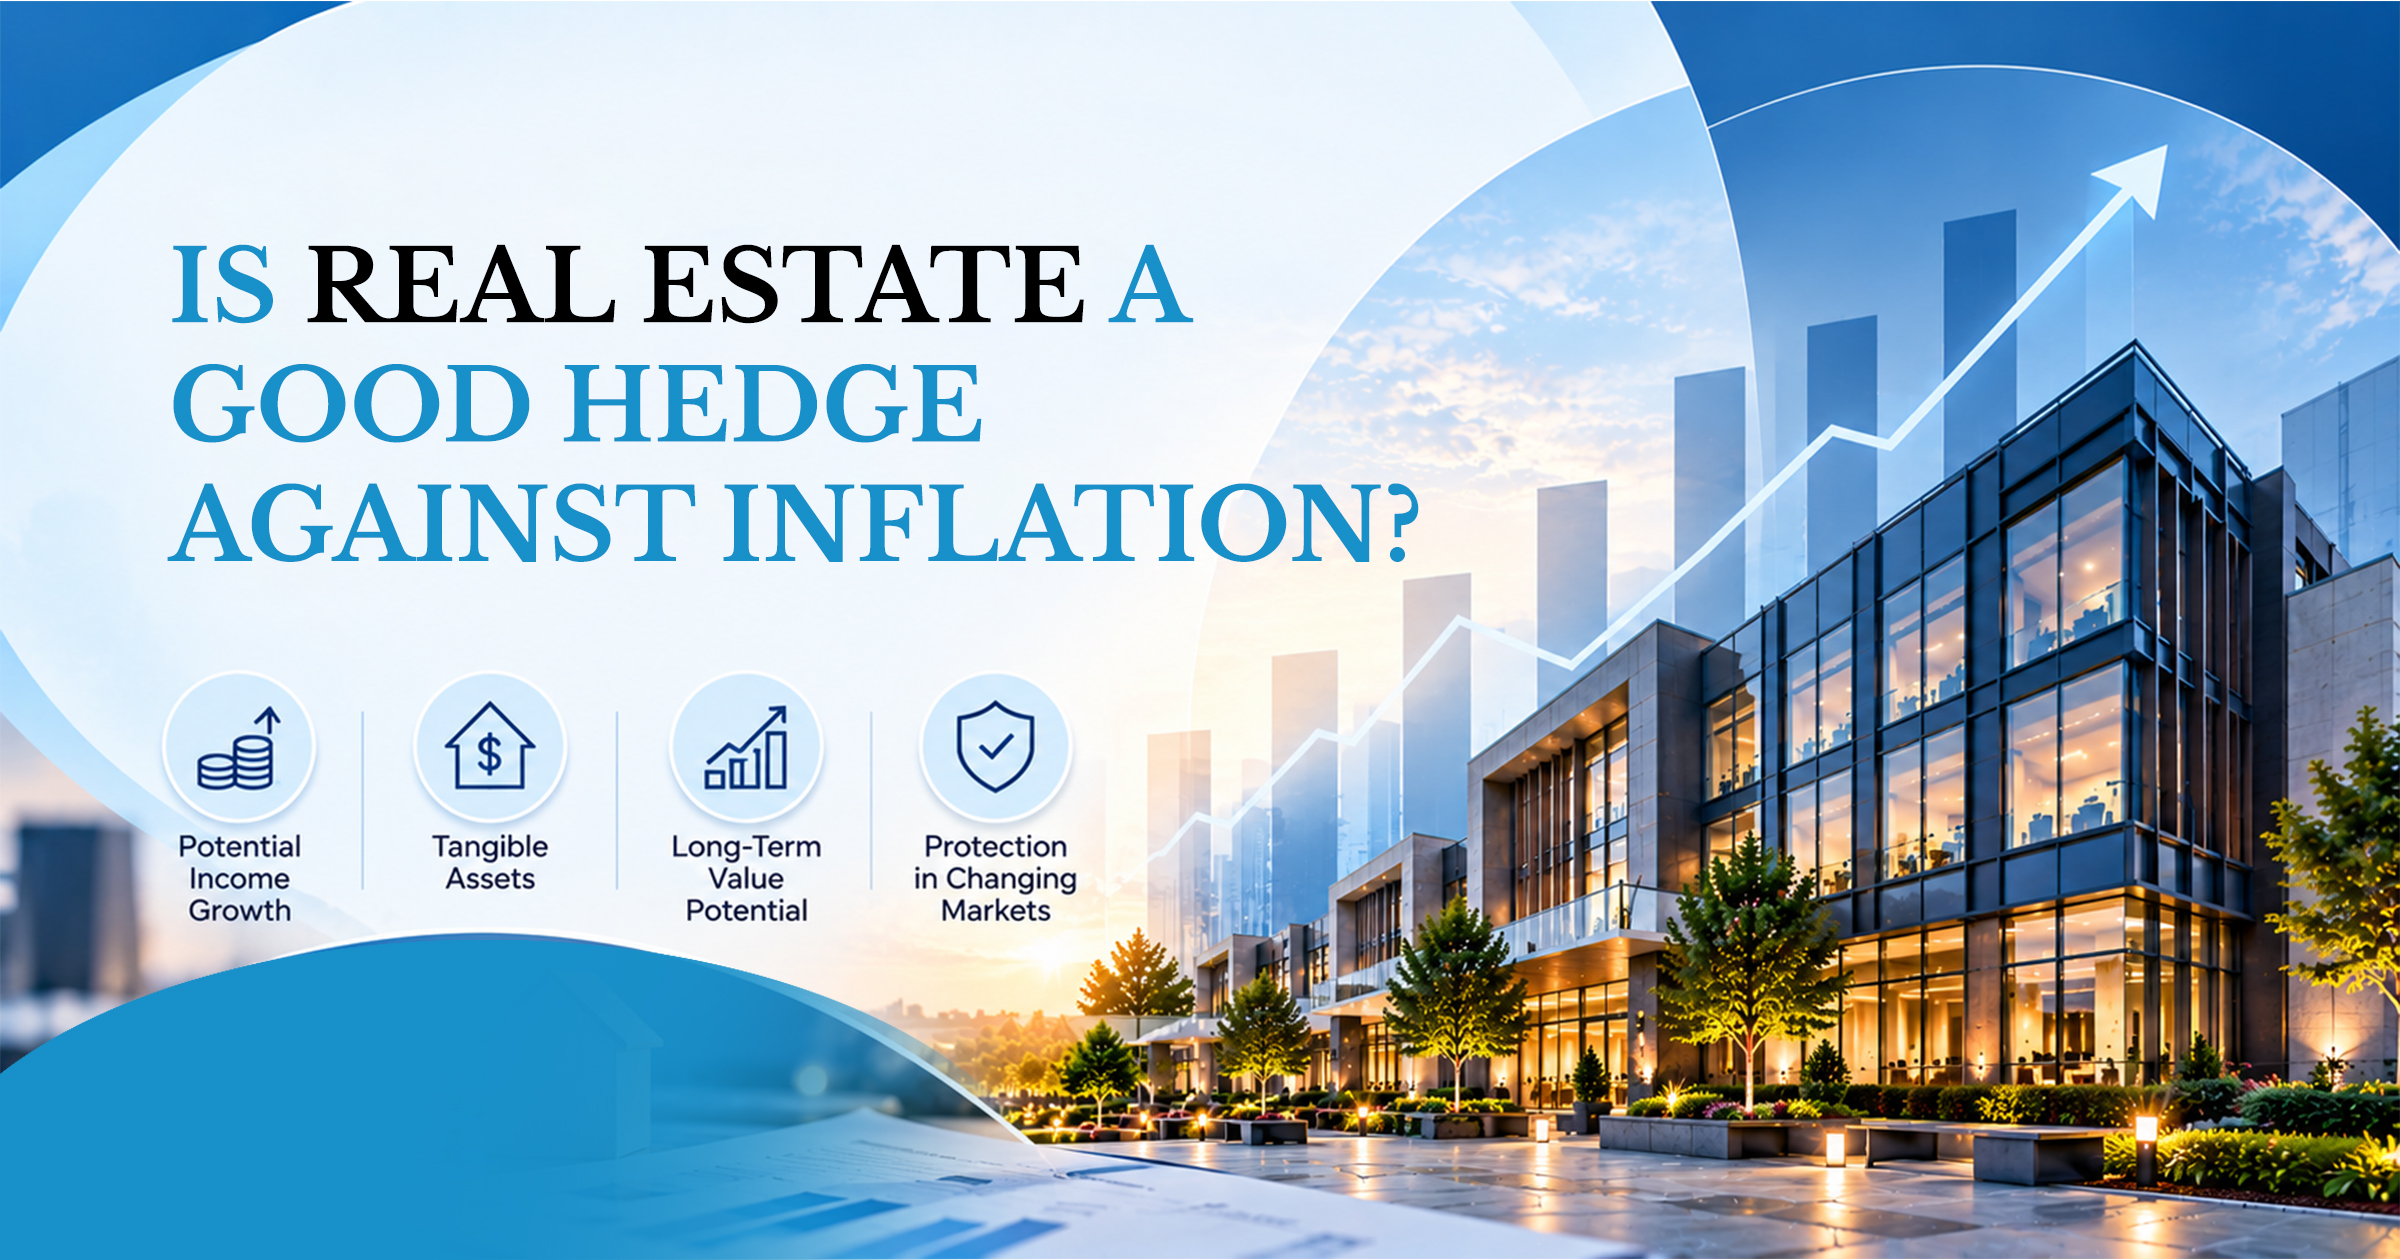
Yes. Real estate is widely considered a good inflation hedge because rents and property values tend to rise as the general cost of living increases. When prices rise, the cost of building new properties rises too, which supports the value of existing properties. At the same time, owners can often raise rents or room rates, helping income keep pace with inflation.
How well real estate works as an inflation hedge depends on the property type, its lease structure, its location, and how it’s financed. Properties that can adjust their income quickly, such as hotels, tend to respond to inflation faster than properties locked into long, fixed leases.
Can Real Estate Help Protect Your Wealth Against Inflation? Schedule a 15-minute meeting with Vairt to discuss real estate opportunities and how property investments may respond to inflation.
Several forces work together to make real estate a natural real estate inflation hedge.
The first is rental income. Housing and lodging are everyday needs, and the cost of shelter makes up a large share of the consumer price index that the U.S. Bureau of Labor Statistics uses to measure inflation. When the cost of living rises, rents and room rates often rise along with it, which means property income can adjust over time.
The second is replacement cost. When the price of land, labor, and building materials goes up, it becomes more expensive to build new properties. That higher cost of new construction tends to support the value of existing buildings, since buyers compare what’s available today with what it would cost to build something similar.
The third is limited supply. In many markets, new construction can’t keep up quickly with demand, especially when building costs are rising. That balance between supply and demand helps support both occupancy and rents.
The fourth applies to properties with fixed-rate financing. When a property’s loan payment stays the same while rents rise, the gap between income and debt costs can widen over time, and the loan becomes smaller in real terms as inflation reduces the value of each dollar.
Not all property types work as an inflation hedge in the same way. The key difference is how quickly each one can adjust its income.
Hotels are often considered one of the most responsive property types because they reprice every night. A hotel can raise room rates as soon as demand and costs rise, rather than waiting for a lease to expire. That makes hotel income especially sensitive to changes in the broader economy.
Short-term rentals work in a similar way, adjusting nightly rates to match demand. Residential communities, such as apartments, usually sign leases of about a year, so rents can reset annually as leases renew. Parking facilities can often adjust daily and monthly rates relatively quickly.
Office, retail, and industrial properties typically use longer, multi-year leases. Many of these leases include built-in rent increases, called escalations, and some use triple-net (NNN) structures where tenants pay most property expenses. These features help income keep up over time, though rents adjust more gradually than nightly-rate properties.
Here’s how the main property types compare:
|
Property Type |
How Often Income Can Adjust |
How It Responds to Inflation |
|
Hotels |
Nightly |
Room rates can adjust quickly with demand |
|
Short-term rentals |
Nightly |
Booking rates adjust with demand |
|
Parking facilities |
Daily or monthly |
Rates can be updated frequently |
|
Residential communities |
Usually annually |
Rents reset as leases renew |
|
Office, retail, and industrial |
Over multi-year leases |
Escalations and NNN terms help over time |
Our guide to the 7 types of income generating property explains how each of these property types earns income in more detail.
Real estate tends to perform well as an inflation hedge over time, and a few property-specific factors help determine how well a particular property fits that role.
Operating costs are one factor to review. Inflation can raise the cost of labor, utilities, insurance, and materials, so properties with experienced management and the ability to adjust rates tend to be better positioned. Interest rates are another, since inflation often leads to higher rates, which can affect financing costs and how buyers value properties.
Location and demand matter too. Rents and room rates can only rise where people want to live, work, and travel, so properties in markets with steady employment and visitor demand are better positioned to pass rising costs through to income. Our breakdown of the best cash flow real estate markets in the U.S. shows how widely income potential varies by location.
Finally, real estate is a long-term asset. Its strength as an inflation hedge shows up over a multi-year holding period, which gives rents, values, and income time to adjust.
Owning real estate directly can be an effective way to protect against inflation, but it comes with practical challenges. Buying a property usually requires a large down payment, closing costs, and cash reserves. Owning it means screening tenants, handling repairs, managing vacancies, and keeping up with rising operating costs.
The property types that respond fastest to inflation are often the hardest to own directly. A hotel can reprice nightly, but buying and running one takes millions of dollars, a brand agreement, and a full-time operating team. For most people, the best inflation-responsive properties have been out of reach.
Professionally managed fractional ownership lets you own a share of a specific property, including hotels and commercial buildings, without buying the entire property or handling operations. You hold a proportional share of the property’s income and value, while an experienced team runs it.
Vairt is built around this model. Each property is evaluated with a 100-point proprietary screening tool and supported by a third-party valuator before it’s listed, and you can learn more on Vairt’s property review process page. When you choose a property, your funds are held in escrow during the 30-day funding window, and if the property isn’t fully funded, committed amounts are returned to your digital wallet at no cost.
Once funded, each property is held in its own LLC, a legal entity created to own one particular property, divided into one million shares allocated in proportion to each participant’s contribution. A professional team manages operations, rental income is distributed monthly to each owner’s digital wallet, and owners track performance through Vairt’s digital dashboard and mobile app.
Vairt’s properties are designed around a five-year holding period, which aligns with the multi-year horizon where real estate’s inflation-hedging strengths tend to show. For owners who want to exit sooner, Vairt offers a 90-day exit option, and owners can also list shares on a secondary market or call a vote among owners to sell the property. You can see every step on Vairt’s How It Works page.
Two of Vairt’s current listings in downtown Peoria, Illinois, show how different income models respond to rising prices. Both list a $25,000 minimum and a five-year holding period.
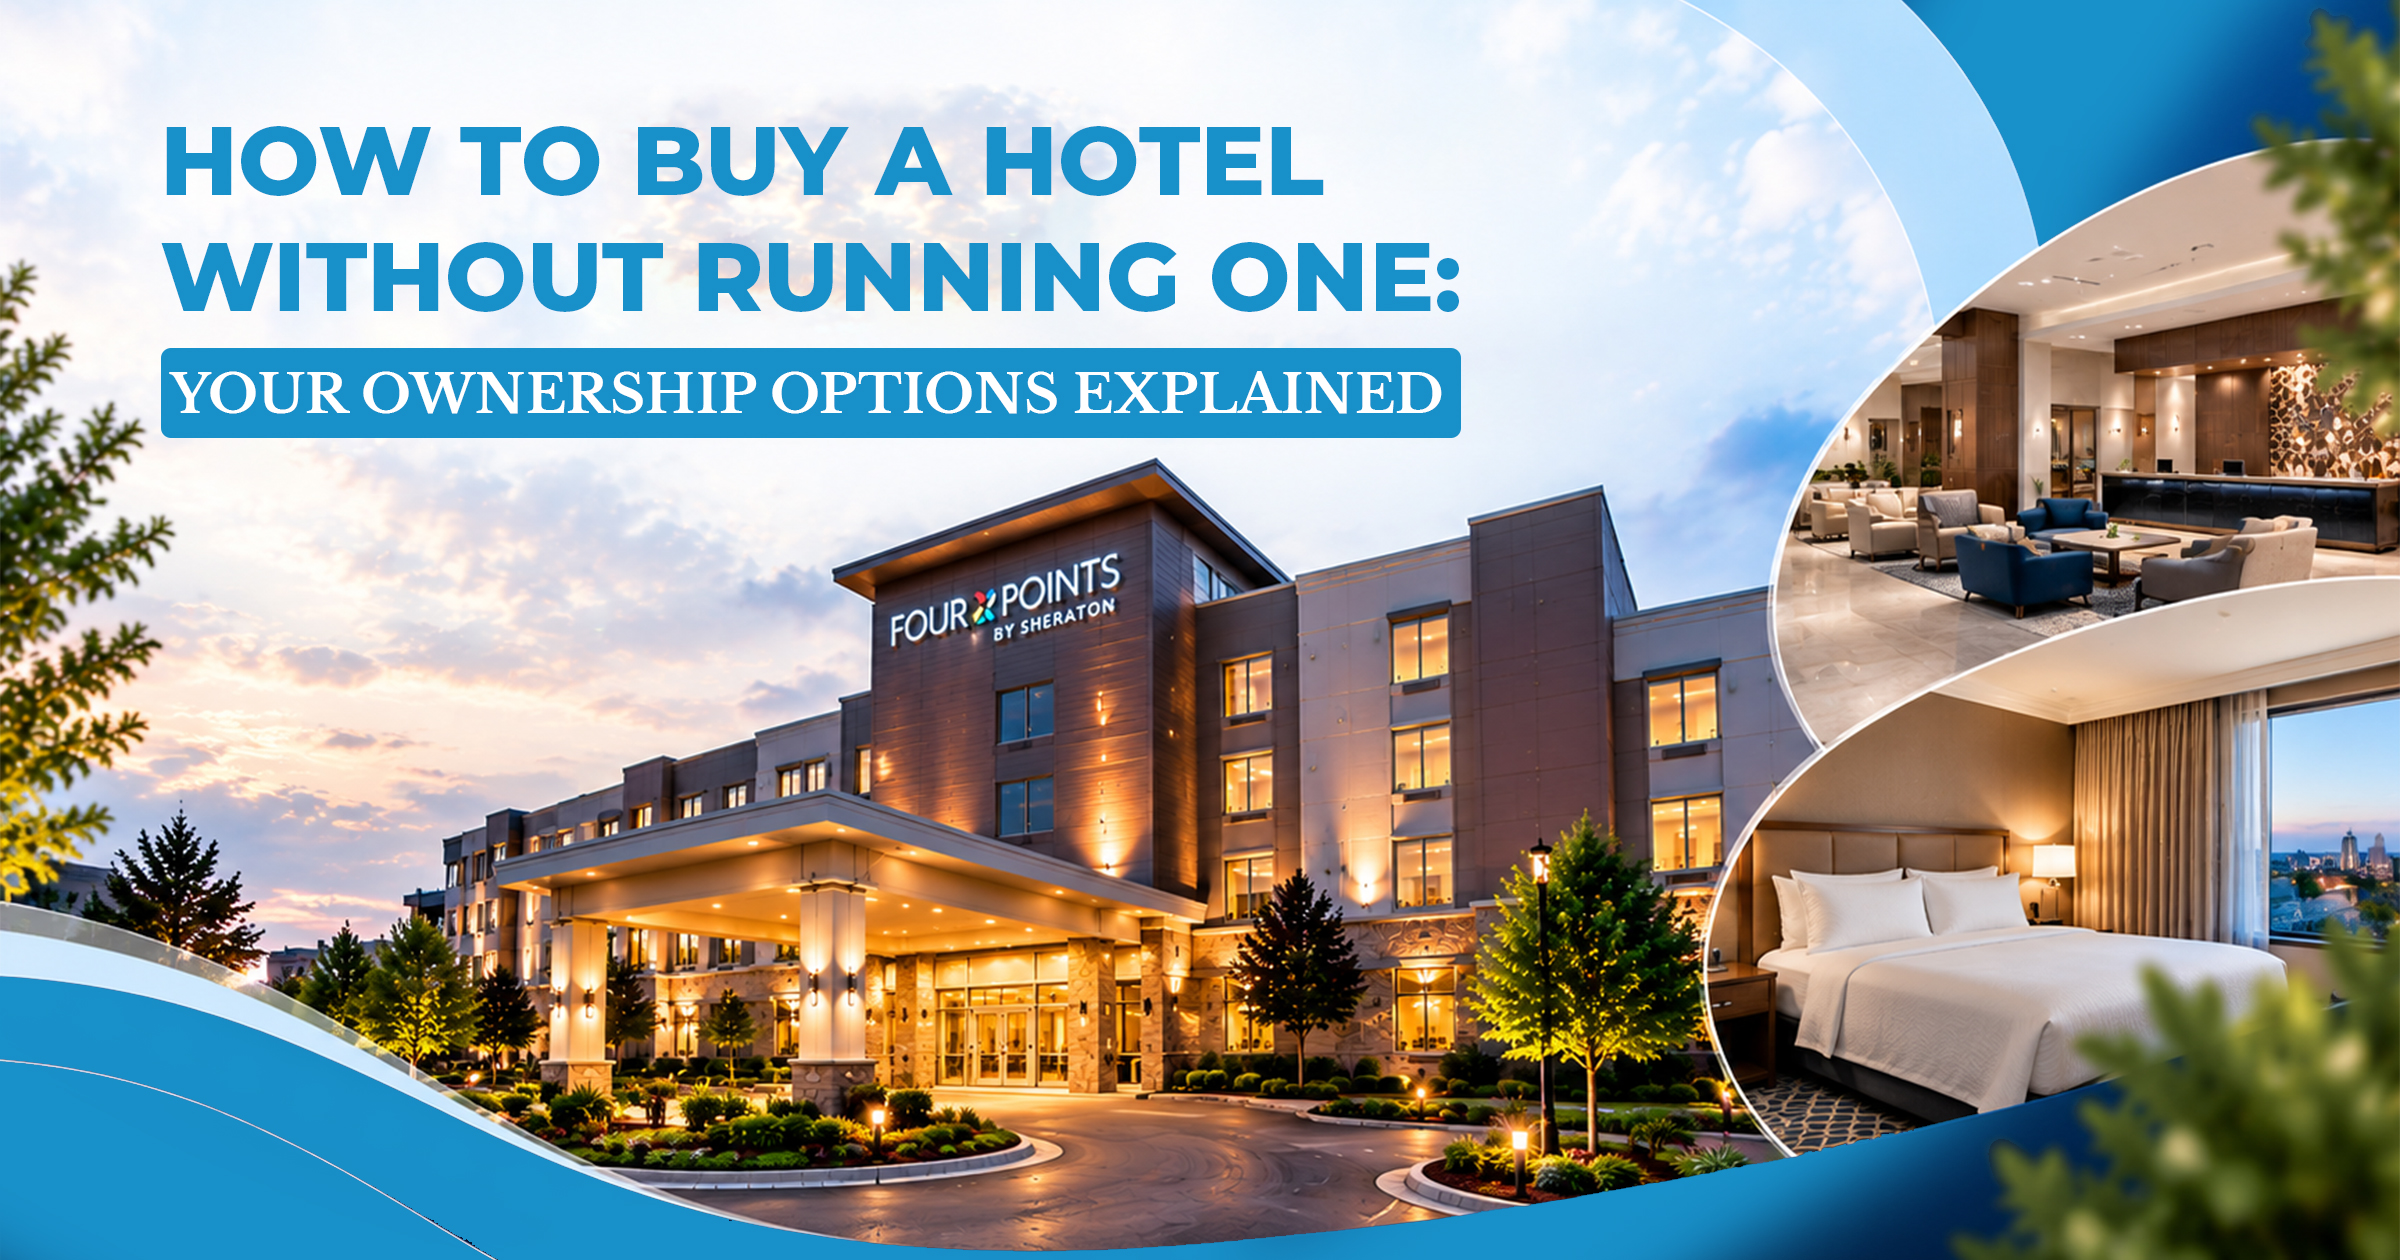
The Four Points by Sheraton in downtown Peoria is a 323-room, full-service hotel operating under a Marriott brand. As a hotel, it sets room rates nightly, which allows its income to respond to changes in demand and costs. It completed a $40 million renovation in 2020 and benefits from a central location with corporate and event-driven demand. Vairt projects annual rental income of 7% to 9% during years one through five, paid as monthly distributions, along with long-term appreciation potential.
Vairt’s commercial office and parking property in downtown Peoria combines about 68,360 square feet of office space with a seven-story parking deck of roughly 552 spaces. Its two income streams respond to inflation at different speeds: parking rates can adjust frequently, while office leases provide longer-term income. Vairt projects annual rental income of 8% to 10% during years one through five, also paid monthly.
Projected figures are based on Vairt’s current estimates, and actual income follows each property’s performance. Owning both types of income in one place is also a form of diversification, an approach we explain in our guide to real estate diversification for busy professionals.
Vairt also lists V Resort Living, a 332-residence community in Sheridan, Illinois, where leases reset as they renew; the Econo Lodge Inn & Suites, a 113-room hotel in Triadelphia, West Virginia; and the 5 Million Star Hotel in Pennsylvania, a 60-unit hospitality development built around dome-style accommodations.
Full property details, including projections, cost breakdowns, holding terms, and eligibility, are available to registered users. Creating a Vairt account takes just a few minutes and lets you compare all of Vairt’s current real estate opportunities side by side.
Worried about inflation eating into the value of your savings? Schedule a free 15-minute call and we’ll walk you through how Vairt’s hotel and commercial properties generate monthly rental income.
Professionally managed real estate is a strong fit for people who want their money tied to tangible properties whose income can adjust with rising prices. It works especially well for busy professionals, people concerned about inflation reducing the value of their savings, and anyone interested in owning part of a hotel or commercial building rather than a single rental home.
It also suits people who are comfortable with a five-year holding period and value having a 90-day exit option available. Those who need daily access to their money, or who prefer fixed income regardless of inflation, may prefer other options. For more on how commercial properties produce income, read our guide to commercial real estate passive income.
Real estate has long been considered a dependable inflation hedge. Rents and room rates tend to rise with the cost of living, higher building costs support property values, and properties like hotels can adjust their income nightly. The challenge for most people has been the cost and work of owning these properties directly.
Professionally managed fractional ownership makes a real estate inflation hedge more accessible. With Vairt, you can own part of a Marriott-branded hotel or a downtown office and parking building, receive projected rental income as monthly distributions, and rely on professional teams for operations. Review each property’s income model, location, and holding period, and then choose the property that fits your goals.
When you’re ready to review real properties, create a Vairt account to unlock full details for every current listing.
Yes. Real estate is widely considered a good inflation hedge because rents and property values tend to rise with the cost of living over time. Higher construction costs also support the value of existing properties. How well a specific property works as a real estate inflation hedge depends on its type, lease structure, location, and financing.
Hotels are often considered among the most inflation-responsive property types because they can adjust room rates nightly. Short-term rentals and parking facilities can also reprice quickly. Residential communities adjust as leases renew, usually annually, while office, retail, and industrial properties rely on multi-year leases with built-in rent increases.
Rental income often rises with inflation over time, since rents and room rates tend to follow the broader cost of living. The speed depends on the lease structure. Nightly-rate properties like hotels can adjust immediately, while properties with long leases adjust gradually through scheduled rent increases. Local demand and operating costs also influence how income changes.
Inflation tends to support property values because it raises the cost of land, labor, and materials needed to build new properties, which makes existing buildings more valuable by comparison. Rising rents can also increase a property’s income and value. Interest rates also play a role, since they influence financing costs and how buyers value properties.
Yes. Through professionally managed fractional ownership, you can own a share of a hotel or commercial building while a professional team handles operations. On Vairt, rental income is distributed monthly to owners. For example, Vairt projects annual rental income of 7% to 9% for its Four Points by Sheraton hotel in years one through five.
Buying a hotel or commercial building directly usually requires millions of dollars. Fractional ownership lowers the starting point considerably. Current listings on Vairt, including a Marriott-branded hotel and a downtown office and parking property in Peoria, Illinois, show a $25,000 minimum. Always confirm the minimum and eligibility on each property listing.
No. Real estate income depends on occupancy, rents or room rates, operating expenses, interest rates, and local market conditions. Projected figures, like the annual rental income ranges Vairt shares for each property, are a helpful way to compare options. Reviewing each property’s income model and holding period helps you make an informed decision.
I'm Muhammad Waqas, a real estate content writer at Vairt with 8 years of experience writing about property ownership and real estate. I cover topics such as fractional real estate, hotel and commercial property ownership, and how to evaluate income-producing properties. My writing focuses on helping U.S. readers understand how professionally managed real estate works, including its benefits, risks, and structure, before they explore an opportunity.
Certain statements contained in this document constitute forward-looking statements. Such forward-looking statements, including our intended actions and performance objectives, projections, targets, estimates, or forecasts involve known and unknown risks, uncertainties and other important factors, including our ability to successfully develop and operate the Vairt Marketplace, our business model and the services we intend to offer. These factors are based on expectations and assumptions that may change and are subject to regulatory uncertainty, changes in our legal environment and the blockchain and real estate industries generally, which could cause our actual results, performance or achievements to differ materially from any future results, performance or achievements expressed or implied by such forward-looking statements. All amounts, numbers, ranges, and values presented in this document are subject to material change and should be taken as preliminary and indicative only. Any such amounts, numbers, ranges, and values are based upon preliminary estimates, remain subject to ongoing analysis and may change materially. All forward-looking statements in this document speak only as of the date hereof. We expressly disclaim any obligation to update any forward-looking statement to reflect any change in our expectation or any change in events, conditions, assumptions or circumstances.
Comments